Categories
Buying a Home in Colorado SpringsPublished October 15, 2026
Colorado Springs Home Insurance: What Buyers Should Check Before Closing
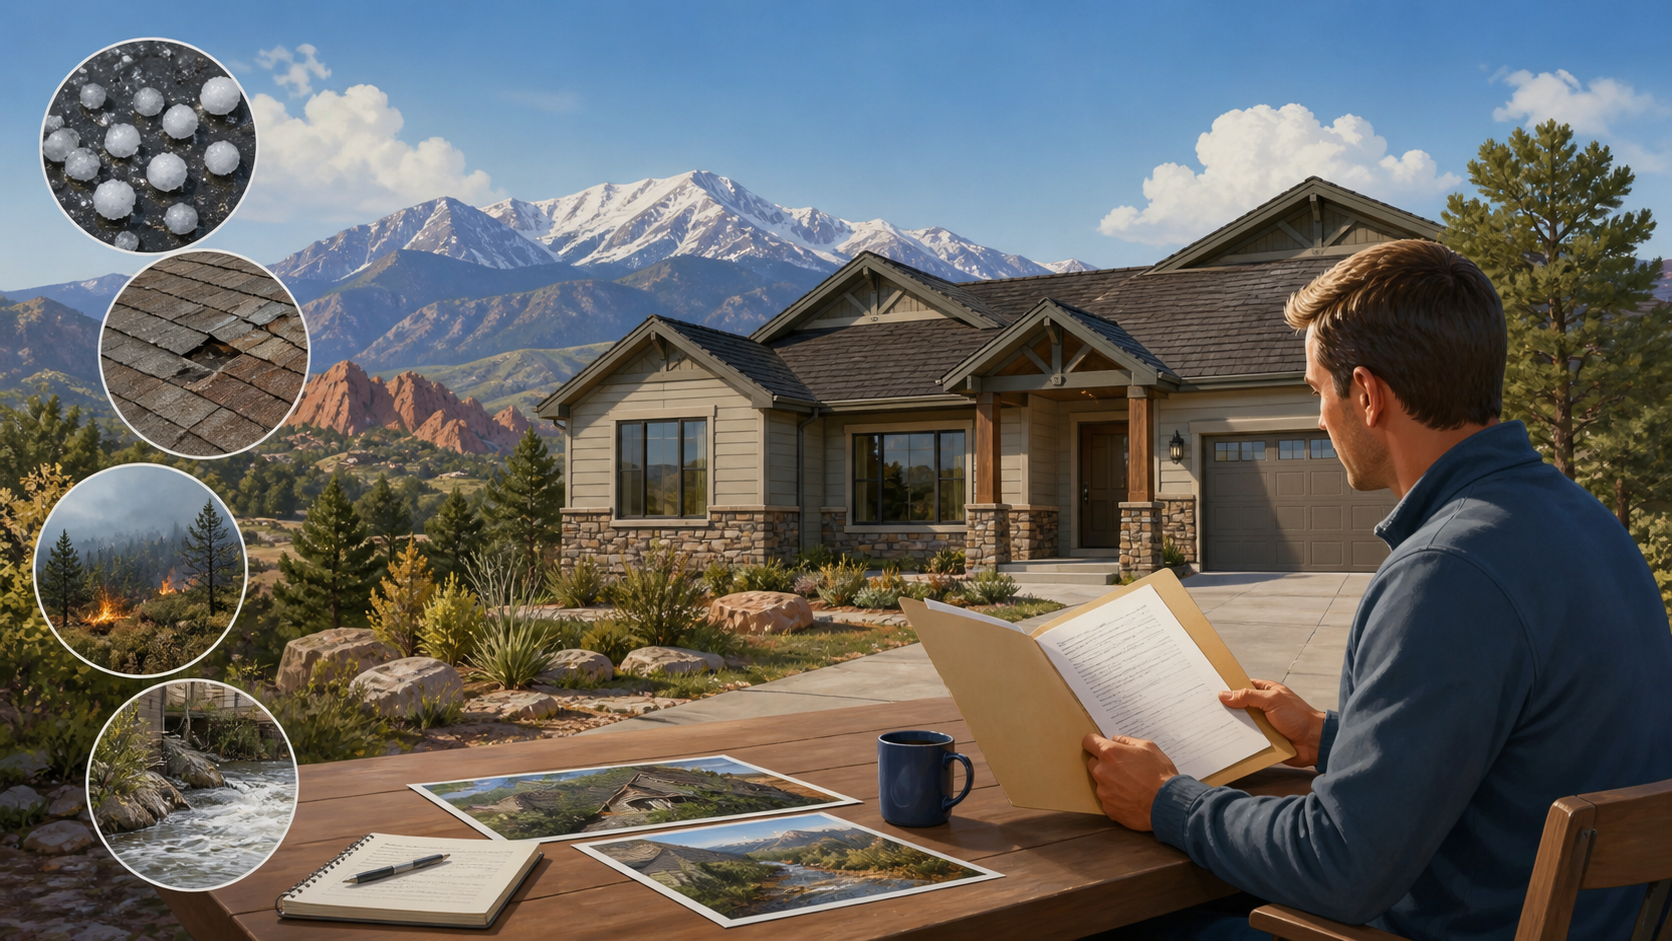
Colorado Springs home insurance deserves a place near the top of a buyer’s checklist—not as a last-minute task after every other decision is made. A home may look straightforward during a showing, yet its roof, location, claims history, rebuilding cost, wildfire exposure, or homeowners association can affect whether coverage is available and what it costs.
That does not mean buyers should assume a property will be difficult to insure. It means they should start early, ask property-specific questions, and compare written quotes before important contract deadlines. The goal is to understand the coverage and the total monthly cost while there is still time to make an informed decision.
Why Colorado Springs Home Insurance Should Be Checked Early
Lenders generally require evidence of acceptable homeowners insurance before closing on a financed purchase. Waiting until the final days can create unnecessary pressure if an insurer needs more information about the roof, prior claims, wildfire mitigation, plumbing, electrical systems, or other property features.
Insurance availability and pricing can also vary from one company to another. The Colorado Division of Insurance regulates the industry and provides consumer resources for homeowners and renters. Its materials are a useful starting point, but only a licensed insurance professional can explain how a specific carrier would evaluate a specific home.
A practical approach is to contact an insurance professional as soon as you are seriously considering a property, then confirm the final premium and coverage before your applicable insurance or loan deadlines.
Start With the Roof
Colorado Springs buyers quickly learn why roof questions matter. Hail, wind, snow, sun exposure, installation quality, and maintenance can all affect a roof over time. An online listing may mention a “newer roof,” but that phrase is not a substitute for documentation.
Ask for available records such as:
- The approximate installation date
- Invoices, warranties, and contractor information
- Permit information when applicable
- Insurance claim documents the seller is able to provide
- Any repair or inspection reports
Your home inspector can evaluate visible roof conditions within the scope of the inspection. Your insurance professional can explain whether roof age, material, condition, or prior claims affect eligibility, deductibles, endorsements, or premium. These are different evaluations, and both can be useful.
Understand Wildfire Exposure Without Making Assumptions
Wildfire considerations are property-specific. A western foothill property, a home near open space, and a house in a more urban setting may present different conditions. Buyers should not rely on a broad neighborhood label or assume that every property near vegetation will receive the same insurance treatment.
The Colorado Springs Fire Department maintains resources for residents in the Wildland Urban Interface and offers programs that may include risk information, on-site consultations, chipping, and mitigation guidance. Buyers can review the City’s Wildland Urban Interface information and the Colorado Springs Fire Department Preparedness Guide.
When evaluating a home, look beyond the view. Consider vegetation near structures, access, slope, deck and fence materials, roof and siding materials, nearby open space, and any current mitigation documentation. Ask the insurer what information it uses and what changes, if any, could affect coverage. Never complete costly mitigation work based only on a casual assumption; verify recommendations with qualified professionals and the applicable insurer.
Check Water and Flood Questions Separately
Standard homeowners policies and flood insurance are not the same product. Surface water, drainage, sewer backup, plumbing leaks, groundwater, and mapped flood risk may be treated differently. Buyers should ask what is covered, excluded, or available by endorsement rather than relying on the general word “water.”
Review grading, downspouts, window wells, sump equipment, drainage paths, and signs of prior moisture with your inspector. For mapped flood information, use the official FEMA Flood Map Service Center and confirm property-specific questions with the appropriate local agency, survey professional, lender, and insurance professional.
A property outside a high-risk mapped area can still experience water or drainage problems. A map is one part of due diligence, not a complete assessment of the site.
Ask About Rebuilding Cost, Not Only Purchase Price
The amount you pay for a home is not necessarily the amount it would cost to rebuild after a covered loss. Labor, materials, demolition, debris removal, code requirements, architectural features, and site access can all affect replacement cost.
Ask the insurance professional to explain the dwelling limit, replacement-cost assumptions, deductibles, ordinance-or-law coverage, personal-property coverage, loss-of-use coverage, and any optional endorsements. If the quote uses information that appears inaccurate—such as the wrong square footage, roof type, or finished basement—ask for it to be corrected.
This is also a good time to inventory special features such as a detached structure, solar panels, a hot tub, a wood stove, a home-based business, or high-value personal property. Each insurer may request different information.
Review HOA and Condo Coverage Carefully
For a condominium or townhome, the association’s master policy does not eliminate the need for individual coverage. Buyers should obtain the current master policy, declarations, deductibles, and available loss-history information, then ask both the association and their insurance professional how responsibilities are divided.
Questions may include:
- What portions of the structure are insured by the association?
- What interior finishes are the owner’s responsibility?
- What is the association’s deductible?
- Could loss-assessment coverage be appropriate?
- Are detached garages, patios, or improvements treated separately?
Association documents and policies can change. Review the current documents for the property and ask qualified insurance and legal professionals to interpret questions that affect you.
Compare More Than the Premium
The lowest annual price is not automatically the best fit. Compare written quotes line by line. Look at coverage limits, deductibles, exclusions, endorsements, claim service options, discounts, and whether the quote is based on replacement cost or another valuation method.
Ask whether hail or wind has a separate deductible and whether that deductible is a fixed dollar amount or a percentage. Confirm how roof losses are settled and whether age or condition changes the calculation. Policy language varies, so request explanations in writing when possible.
Do not cancel existing coverage or assume a binder is final until the insurance professional confirms the effective date and all remaining requirements.
A Buyer’s Colorado Springs Insurance Checklist
- Request quotes early in the contract period
- Provide accurate property details to the insurer
- Review roof age, condition, permits, and available documentation
- Check property-specific wildfire resources and mitigation history
- Review drainage, moisture, sewer-backup, and flood questions
- Confirm dwelling limits, deductibles, exclusions, and endorsements
- Obtain current HOA or condo insurance documents when applicable
- Ask your lender when proof of coverage is required
- Keep the final quote and policy documents with your closing records
Frequently Asked Questions About Colorado Springs Home Insurance
When should I get an insurance quote while buying a home?
Start as early as practical after identifying a property, and confirm the final coverage and premium before the deadlines in your contract and loan process. Your agent, lender, and insurance professional can help coordinate timing.
Does every Colorado Springs home have the same wildfire risk?
No. Exposure and insurer evaluation are property-specific. Use official local resources, review the physical site, and ask the insurer how it assesses the address.
Will a home inspection tell me whether a house is insurable?
No. An inspection provides information about visible property conditions within the inspector’s scope. An insurance company makes its own underwriting decision. Share relevant inspection findings with the insurer when requested.
Is flood damage covered by a standard homeowners policy?
Do not assume it is. Ask a licensed insurance professional to explain flood coverage, water exclusions, sewer-backup options, and property-specific recommendations.
Can an insurer change a quote before closing?
A preliminary quote may change if the carrier receives new property information, completes an inspection, reviews records, or updates underwriting. Ask what remains outstanding and obtain final confirmation.
Build Colorado Springs Home Insurance Into Your Buying Plan
Colorado Springs home insurance is easier to evaluate when it is part of the buying plan from the beginning. Early quotes give you time to understand the roof, wildfire and water considerations, HOA responsibilities, deductibles, and total monthly cost before closing.
Colorado Springs Home Search Group with Keller Williams Partners helps buyers organize the local details that affect a purchase. If you are comparing homes in Colorado Springs, Fountain, Security-Widefield, Monument, Falcon, Peyton, Meridian Ranch, Manitou Springs, Woodland Park, or nearby El Paso County communities, contact our team for a personalized home-buying or relocation plan.
Information researched and last verified August 31, 2026. This article is for general educational purposes and is not insurance, legal, lending, inspection, tax, or financial advice. Coverage, underwriting, hazards, maps, association policies, and program details can change. Verify property-specific information with licensed insurance professionals, your lender, qualified inspectors, the association, and the appropriate government agencies.
or another way